September 2026 Hay Report
Basis: SE Colorado Good/Premium commercial large-square alfalfa, completed FOB-farm trades ≥100 tons, $/ton · Supersedes: the Aug 27 grid · Method: every number below was re-pulled from the primary file this cycle and the load-bearing ones were read twice; the verification table is research/17 §11. Confidence on every forecast row is LOW — our own rule (L9) until we have twenty comparable graded outcomes.
CORRECTION (same day, Sep 19, 2026 — after an independent review, see research/18). The first version of this report claimed a "$250–260 regional floor"; a 380-ton Good/Premium 4x4 lot printed at $170 FOB in Oklahoma the same week and was left out of parity. It presented a "$222 export netback" that subtracted freight from an origin price with no known destination. It said Southeast cash "peaked Nov–Dec 2022 and was $40 lower by February" by comparing a 1,000-ton new-crop lot with a 25-ton old-crop lot. All three are withdrawn below. A follow-up review found more (a false "$240–300 for every large lot" claim — Nebraska sold 1,000 t of rounds at $160; a stale chart; an overwritten archive), also fixed. Nowcast revised $280 → $270. The scorecard, USDA transactions, NASS prices and canal arithmetic were confirmed by the review.
Bottom line
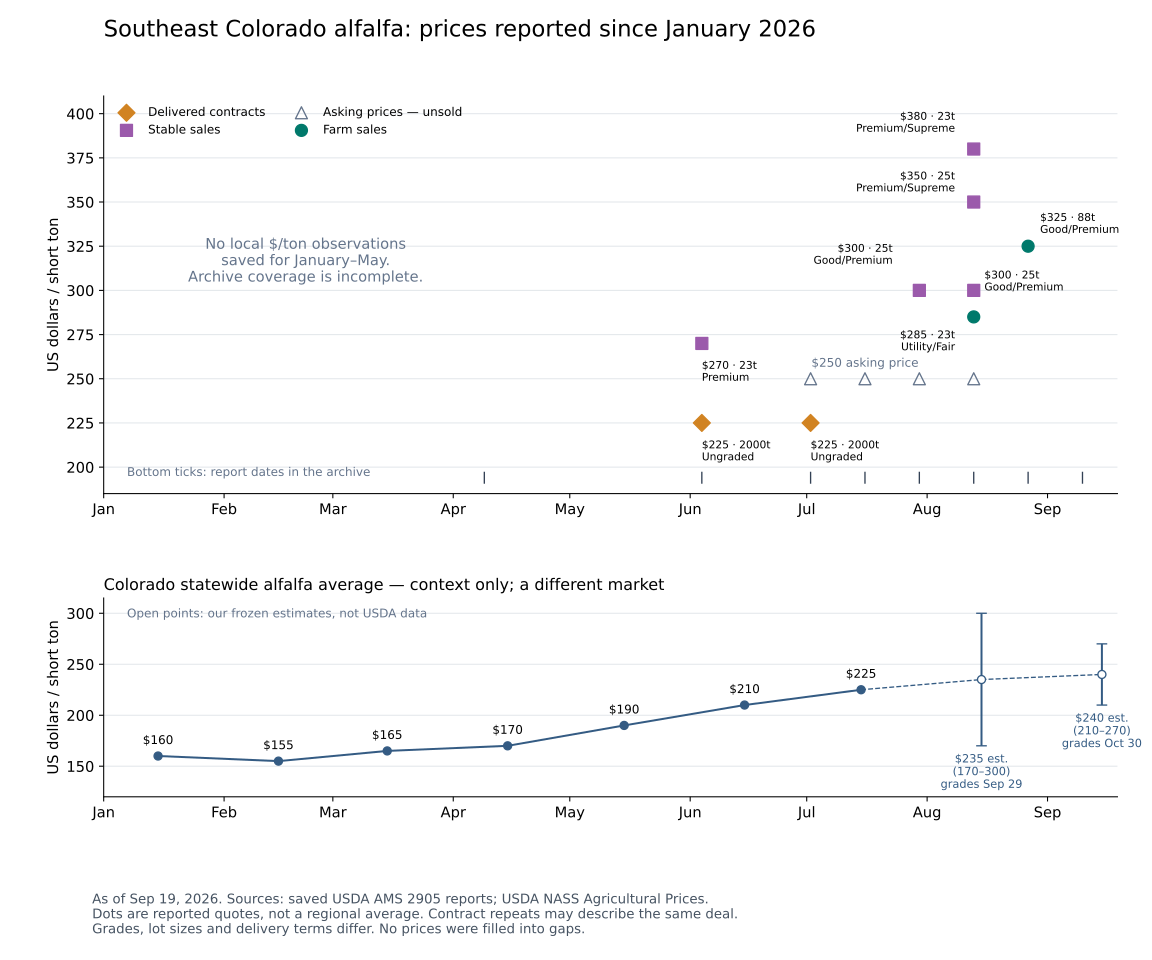
The target price did not print, and a new six-year history says it almost never does. USDA's Sep 10 Colorado report carried no Southeast farm-gate alfalfa trade at all. We retrieved 242 Colorado reports back to July 2020 (USDA's ESMIS archive through Sep 2025, then Wayback and local copies; Oct–Nov 2025, Jan–Mar 2026 and May 2026 are missing) and found that a Southeast FOB-farm Good-or-better large-square trade of 100 tons or more has printed 6 times in 242 reports — about once a year. Grading a local price against that target was honest in principle and unworkable in practice. From here the local calls are "prints / doesn't print" with the base rate stated, and the local price is a nowcast built from named comparable trades.
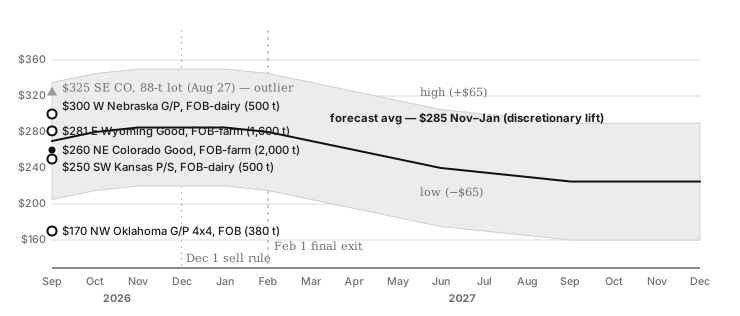
Our estimate is lower than we said three weeks ago. The 88-ton $325 lot the last report leaned on is tied (with a 24-ton Premium lot in Nov 2022) for the highest Southeast farm-gate print in the retrieved ledger. The biggest commercial Colorado trade of the year came Sep 10: 2,000 tons of Good 3x4 at $260 FOB-farm (Northeast region). The comparison set is defined as: conventional alfalfa, completed per-ton trade, large square bales only (3x4/4x4), ≥100 tons, priced at origin, from the Sep 10–18 reports. On that rule, Good/Premium lots ran $170 (380 t 4x4, Oklahoma) to $330 (200 t, western Nebraska) and average $270 tonnage-weighted; Good lots ran $230–285 and average $269; the ≥500-ton Good-or-better large-square lots ran $250–300 (Kansas Fair/Good squares sold lower: 500 t at $195 FOB, 3,575 t at $233 delivered). Large rounds are excluded by rule and ran $160–240 (Nebraska sold 1,000 t of Good rounds at $160). Our estimate for SE Colorado Good/Premium large squares: $270/ton, Good ~$265, uncertainty ±$65. This is a selected regional average, not an observed local price; no local trade printed, so no local decline is measured.
Timing, corrected. The 2022–23 local rows (1,000 t Good/Premium new crop at $300 on Nov 17; 50 t Premium at $320 in December; 25 t Good old crop at $260 in February) are consistent with a November–December peak but mix grade, crop age, bale and lot size, so they do not establish one. The same-grade Good rows went $225 (Sep) → $250 (Oct) → $260 (Feb).
All charts, forecast comparisons and source data
Report card
Eleven pre-registered rows resolved this cycle. Scores are computed from the ledger, never typed.
| # | Prediction | Outcome |
|---|---|---|
| 14 | Colorado alfalfa July state price $220 (212–230) | HIT — $225 |
| 15 | Colorado all-hay July $217 (209–228) | HIT — $222 |
| 16 | Kansas alfalfa July $140 (130–155) | NEAR — $126 (low) |
| 20 | A SE farm-gate alfalfa trade prints again | MISS — none |
| 21 | …its price $315 (250–380) | NO-PRINT |
| 22 | NE dairy trade $330 (265–395) | NO-PRINT (only NE trade: 2,000 t Good at $260 FOB-farm) |
| 23 | Weekly confirmed volume 2,500 t (800–4,200) | MISS — 8,500 t (4,000 t organic contracts + 500 t organic trade) |
| 24 | Demand "Good" or better | HIT — "Good to Very Good" |
| 25 | El Niño Advisory continues | HIT |
| 26 | Weekly Niño-3.4 +2.7 (1.4–4.0) | HIT — +2.7 exactly |
| 27 | "Historic event" odds 69% (59–79) | HIT — 75% |
Standing record: 6 of 16 two-sided ranges contained the outcome (+2 NEAR). The economically central cluster is 1-for-5. Two things to say plainly. First, the statewide-price rows were the easy ones, and we got them: our points ($220/$217) landed within $5 (pure June persistence would have missed by $15/$14). Second, the Kansas row is the tell: the Kansas state average moved $1 (to $126) while Kansas cash traded $200–260. The state average is not lagging cash and about to catch up; it is a different, lower-quality-weighted series. Our August rows ($235 Colorado alfalfa, grading Sep 29) test that directly.
The interval floor stays ±$65. Our calibration script mechanically cut it to ±$41 after three easy hits; the rule that floors only fall once coverage clears 70% existed only as a caveat in the file. It is now enforced in code.
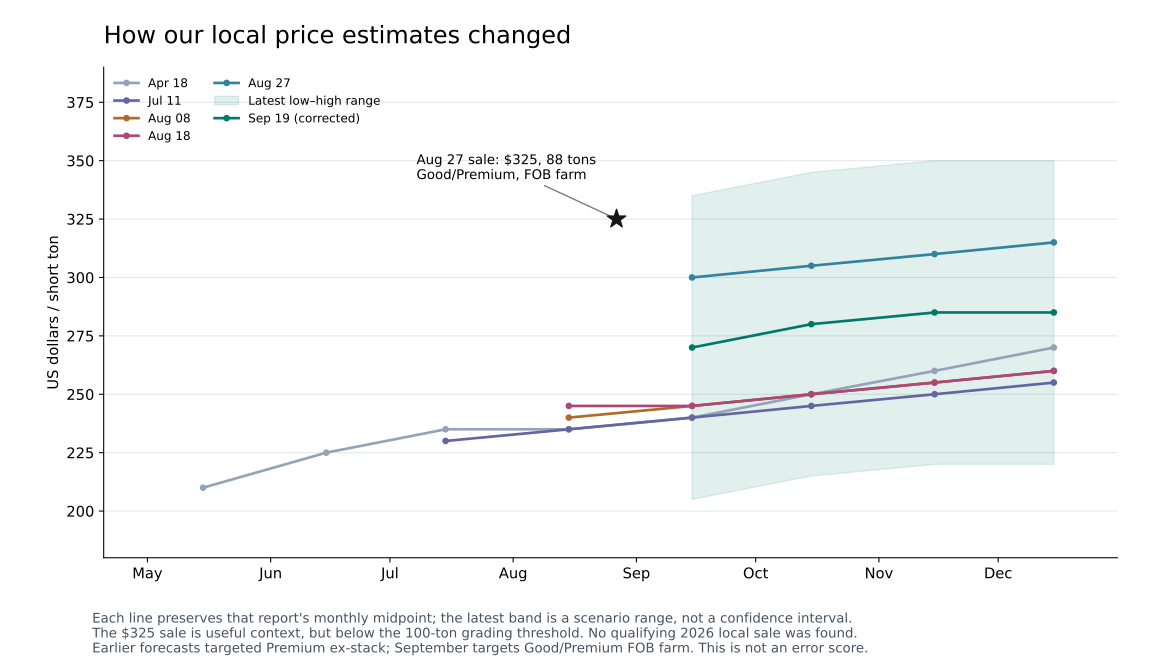
The forecast
| Month | Low | Mid | High |
|---|---|---|---|
| Sep 2026 | 205 | 270 | 335 |
| Oct 2026 | 215 | 280 | 345 |
| Nov 2026 | 220 | 285 | 350 |
| Dec 2026 | 220 | 285 | 350 |
| Jan 2027 | 220 | 285 | 350 |
| Feb 2027 | 215 | 280 | 345 |
| Mar 2027 | 205 | 270 | 335 |
| Apr 2027 | 195 | 260 | 325 |
| May 2027 | 185 | 250 | 315 |
| Jun 2027 | 175 | 240 | 305 |
| H2 2027 | 160–170 | 225–235 | 290–300 |
Built in three layers, shown separately: (1) statewide anchor — the Colorado average ($225 in July) followed the two prior rising-into-July years (2018, 2022) to about $255–265 by winter; (2) local nowcast — $270 for Good/Premium from the tonnage-weighted ≥100-ton comparable set at origin ($270 G/P, $269 Good, large squares only, including the $170 Oklahoma lot; rounds excluded by rule), a +$30 basis over the $240 state-grid September midpoint, inside the range the 2022 drought produced; (3) seasonal shape — a discretionary +6% into November–January (Northeast large-tonnage trades rose a median +6% into winter, up 5 of 6 seasons; the Southeast rows are too mixed to use), rolling off from March on the drought outlook, also discretionary. Both moves are recorded in data/current/forecast_adjustments.json as exceptions to the indicator policy.
Why lower after four cycles of being too low: the last report anchored on a print tied for the highest in six years, on 88 tons. The direction of surprise this cycle was mixed (state prices and ENSO came in above our points; the one big Colorado trade came in below the mid), so the bias rule doesn't fire. Demand is still the driver — Oklahoma "cattle producers are calling all hay producers," Kansas "inventories began to diminish," Nebraska semis "heading west… not usual for September," Wyoming ranchers outbidding dairies, August feedlot placements the lowest since 1996 — but the same Oklahoma report also sold 380 tons of Good/Premium at $170, so the nowcast is the tonnage-weighted comp set, not the top of any bracket.
Moves it down: a Colorado ≥500-ton farm-gate print at or under $240; Kansas/Oklahoma wheat pasture reports after El Niño rain (the official drought outlook now calls for improvement or removal across KS/OK/TX by year-end); milk under $15.50; Dec 1 snowpack ≥100%. Moves it up: any ≥500-ton print at or above $300; Colorado's August state price at or above $250; Oklahoma still "calling all producers" on Oct 2.
Conditions behind the price
- Demand: Colorado pasture 50% poor/very-poor (57% a week earlier; 26% last year); Oklahoma 64%, Wyoming 63%, Nebraska 59%, Texas 58%. Drought index Sep 15: Oklahoma 353, New Mexico 324, Wyoming 302, Texas 242 and worsening, Kansas 173. August placements 1.62 M (−9%, record low), marketings −3%; feeders up $5 since Aug 27 even as the Santa Teresa port reopens Sep 24.
- Counterweights: Class III milk fell $1.20 (Nov $15.96); Dec corn $5.27½, off its $5.49¾ Sep 2 high; the national auction index fell to $170 with the alfalfa sub-index at $160; fertilizer index −9.6% in August. Diesel hit a record $6.285 — it widens the gap between what imported hay costs and what shipped-out hay nets; it does not set direction.
- Water: the Fort Lyon Canal is dry (0 cfs since Sep 11). June–September diversions were 25% of the 2010–25 average, the second-worst season since 2010. John Martin 19,412 AF (5.6% of pool). Pueblo 161k AF, down 29k on the year. But August brought 4.47" at Lamar Airport and Bent County's drought category collapsed from 80% D2-or-worse to 19% in three weeks — the county is essentially D1 while the state remains 44% D3–D4.
- El Niño: weekly Niño-3.4 +2.9; >90% odds of a very strong event; 75% odds of the strongest since 1950 (up from 69%). The Sep 17 outlooks lean 40–50% wet for SE Colorado October through February, and the seasonal drought outlook calls for improvement or removal across Kansas, Oklahoma, and Texas by Dec 31. No local snowpack probability is claimed; only the Dec 1 and Feb 1 readings count.
What we’re watching
- Sep 24: Colorado hay report.
- Sep 29: USDA August prices grade rows #17–19.
- Oct 8–9: CPC ENSO discussion, Colorado hay report and the USDA hay production forecast.
- Oct 30: USDA September prices.
- Dec 1 / Feb 1: Arkansas basin snowpack readings.
Method: six parallel pulls (AMS all seven states, NASS, CPC, water, macro, and the 2020–2026 report archive), every load-bearing line re-read against the saved PDF or text file; hashes and URLs in data/2026-09-19/. Soft spots: the September freight rate is derived ($3.60/mi; last published $3.54); Class III Nov/Dec are quote feeds, not settlements; July export tonnage could not be found; the 242-report ledger was parser-built with six rows hand-checked. The statistical model's forward path is not credible this cycle (it climbs without bound on the drought index and diesel) and was used only as a direction check.